
Racket Sports Market Overview
The global Racket Sports Market comprises equipment and associated products used across tennis, badminton, padel, table tennis, squash, pickleball, and other racket-based disciplines. The market is supported by increasing sports participation, recreational engagement, expansion of courts and clubs, youth development programs, professional competitions, and continuous product innovation.
Racket sports provide a broad equipment ecosystem covering rackets and paddles, balls and shuttlecocks, strings, grips, bags, footwear, apparel, and protective accessories. Tennis provides a large established participation base, while badminton, padel, pickleball, and table tennis are creating additional equipment-demand opportunities across developed and emerging markets.
Participation growth remains a key commercial mechanism because every new player can generate demand for initial equipment, while regular players create recurring requirements for replacement rackets, strings, grips, balls, shuttlecocks, footwear, and accessories. The ITF identified more than 106 million tennis players across 199 countries, while the International Padel Federation reported 38 million padel players globally in June 2026.
The market is also benefiting from the expansion of digital product discovery, specialty sports stores, clubs, academies, and online channels. Manufacturers are increasingly using advanced frame materials, aerodynamic designs, vibration control, weight distribution, spin technologies, and player-specific product configurations to encourage equipment upgrades and premium purchases.
Racket Sports Market Size
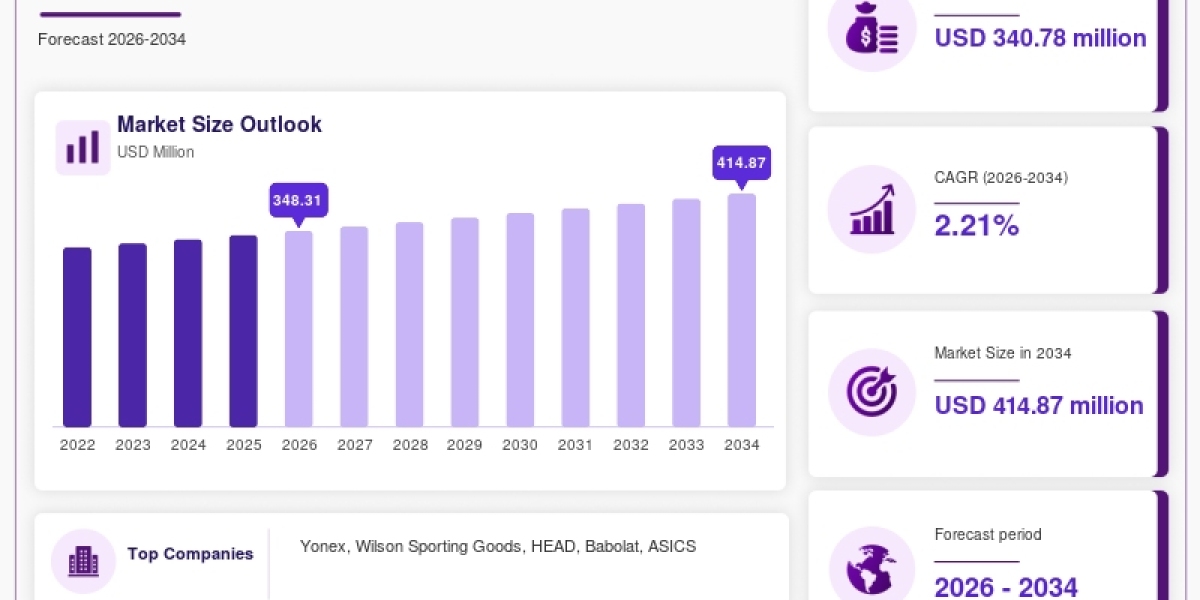
The global Racket Sports Market size was valued at USD 340.78 million in 2025 and is projected to grow from USD 348.31 million in 2026 to USD 414.87 million by 2034, registering a CAGR of 2.21% during 2026–2034. Expansion of racket-sport participation, sports facilities, youth programs, recreational engagement, and product innovation is supporting market growth.
North America dominated the market with approximately 31% share in 2025, while APAC is expected to be the fastest-growing region at approximately 4.8% CAGR through 2034. Tennis held the leading 38% market share in 2025, while Padel is projected to grow fastest at approximately 11.6% CAGR.
Rackets & Paddles represented approximately 44% of the market in 2025, while Balls & Shuttlecocks are projected to grow fastest at approximately 3.4% CAGR. Specialty Sports Stores accounted for approximately 42% of the market, while Online is projected to grow fastest at approximately 5.2% CAGR. Recreational Players held approximately 61% share in 2025, while Junior Players are projected to grow fastest at approximately 4.6% CAGR.
Racket Sports Market Trends
Expansion of Multi-Sport Racket Participation
Consumers are increasingly participating in multiple racket sports, creating opportunities for manufacturers and retailers to expand beyond traditional single-sport equipment portfolios. Tennis, badminton, padel, pickleball, table tennis, and squash each require different equipment specifications, allowing brands to capture additional spending from consumers who participate across disciplines.
Padel and pickleball are particularly important sources of incremental equipment demand. The International Padel Federation reported 38 million players across 100 affiliated federations in June 2026, while the U.S. recorded 24.3 million pickleball participants in 2025.
Manufacturers are responding by developing broader product portfolios. DECATHLON's KUIKMA brand, initially developed around padel, has expanded its expertise across tennis, badminton, pickleball, table tennis, squash, and beach tennis.
Technology-Led Product Innovation and Premiumization
Racket manufacturers are increasingly competing through frame geometry, advanced materials, weight distribution, vibration control, aerodynamic performance, spin generation, durability, and player-specific designs. These technologies provide consumers with reasons to upgrade equipment even when total participation growth is moderate.
Yonex's EZONE and VCORE product lines demonstrate how manufacturers use larger sweet spots, updated frame geometry, vibration-damping materials, aerodynamic designs, and spin-focused technologies to differentiate products.
Premium equipment also provides manufacturers with an opportunity to increase revenue per active participant. Players seeking improved power, control, comfort, spin, maneuverability, and durability may replace older equipment with newer technology-driven models.
Racket Sports Market Drivers
Expansion of Racket-Sport Participation
Participation is the fundamental demand mechanism for racket equipment because every new player requires initial equipment, while regular players create replacement demand for strings, grips, balls, shuttlecocks, footwear, bags, and other accessories.
Global tennis participation reached more than 106 million players, and the ITF is targeting 120 million players by 2030 through its development strategy. In the U.S., tennis participation reached 27.3 million players in 2025, including 4.9 million first-time players.
Badminton provides another large participation base, with BWF reporting approximately 300 million participants worldwide. Increasing participation among women and younger players is also expanding demand for junior rackets, lighter equipment, differentiated apparel, and accessible product ranges.
Padel and Pickleball Are Expanding the Addressable Equipment Base
Emerging and rapidly expanding racket-based sports are creating additional equipment demand rather than simply shifting consumers between established disciplines. The International Padel Federation reported more than 35 million active padel players in 2025 and 38 million in June 2026.
Pickleball is also expanding rapidly in the U.S. SFIA reported 24.3 million pickleball participants in 2025 compared with 4.2 million in 2020. The growth of these sports creates demand for dedicated rackets or paddles, balls, footwear, bags, apparel, and accessories.
The expansion of clubs and courts further strengthens the equipment ecosystem. Manufacturers can develop dedicated product portfolios for each sport while retailers can increase basket sizes through cross-selling complementary equipment.
Product Innovation Supports Replacement and Premiumization
Manufacturers increasingly use technology to differentiate racket products through frame construction, materials, balance, vibration control, spin generation, aerodynamics, and durability. These innovations encourage existing players to upgrade equipment even when participation growth is relatively moderate.
Yonex's eighth-generation EZONE introduced an expanded sweet spot, updated frame geometry, and vibration-damping materials, while its eighth-generation VCORE focused on spin generation and aerodynamic improvements.
Wilson has also expanded technology-led tennis and padel products, including its Defyer tennis racket and ENDURE padel franchise. Product innovation therefore creates an additional replacement mechanism and allows manufacturers to increase revenue per active participant.
Racket Sports Market Restraints
Mature Sports Have Relatively Long Equipment Replacement Cycles
Racket equipment is relatively durable compared with many sporting consumables. Recreational tennis or squash players may continue using the same racket for several seasons when the frame remains structurally sound.
This limits the direct relationship between participation growth and annual racket sales. Strings, grips, balls, and shuttlecocks have more frequent replacement cycles, but these products generally have lower unit values than rackets.
Manufacturers therefore depend on technology upgrades, new product launches, professional-player influence, and improvements in recreational engagement to encourage replacement purchases. The overall CAGR of 2.21% reflects the mature replacement structure of established racket sports despite stronger participation growth in selected disciplines.
Equipment Demand Is Fragmented Across Sports and Regional Preferences
Racket sports have different equipment specifications, playing environments, player preferences, and purchasing behaviors. Tennis requires rackets and balls, badminton uses lightweight rackets and shuttlecocks, table tennis requires blades and rubbers, while padel and pickleball use distinct racket or paddle designs.
This fragmentation requires manufacturers to develop multiple product architectures and retailers to maintain inventory across different sports. Product-development requirements can increase complexity, particularly when businesses need sufficient inventory depth across several disciplines.
Regional differences also affect demand. Asia has strong badminton and table tennis participation, North America has rapidly expanded pickleball, and Europe has established tennis and growing padel ecosystems.
Racket Sports Market Opportunities
Cross-Sport Participation and Multi-Category Equipment Portfolios
Increasing participation across multiple racket sports creates opportunities for manufacturers and retailers to develop broader product portfolios. Consumers participating in tennis, padel, pickleball, badminton, or table tennis can purchase equipment across multiple categories.
DECATHLON's KUIKMA expansion from padel into several racket sports demonstrates the opportunity to use established technology, distribution, and brand infrastructure across disciplines.
Retailers can also increase basket size by combining rackets with footwear, bags, strings, grips, balls, shuttlecocks, apparel, and protective accessories. Digital product-finder tools can further support consumers by recommending equipment according to playing level, sport, swing characteristics, and performance requirements.
Women's and Youth Participation Creates New Demand
Women and younger players represent important opportunities for market expansion. USTA reported that female tennis participation increased by 1.1 million in 2025, while 4.9 million U.S. players picked up a racket for the first time during the year.
The ITF Junior Tennis Initiative introduced more than 318,000 unique players in 2024, with female participation accounting for approximately 45%. Youth-development programs can therefore create both immediate equipment demand and long-term customer relationships.
Demand opportunities include junior rackets, lightweight frames, beginner equipment, women-focused apparel, accessible price points, and products designed for developing players. Similar participation programs in badminton and table tennis can expand equipment adoption in emerging markets.
Challenges in Racket Sports Market
Fragmented Demand and Balancing Product Innovation With Replacement Cycles
Manufacturers must balance product innovation, inventory requirements, sport-specific specifications, price sensitivity, and relatively long equipment replacement cycles. A single product architecture cannot meet the requirements of tennis, badminton, padel, pickleball, table tennis, and squash players.
The durability of rackets can also limit replacement frequency among recreational players. Companies therefore need to demonstrate meaningful performance improvements through technology, comfort, control, spin, power, durability, and player-specific design.
The challenge is particularly important in mature markets where participation may continue growing while consumers retain equipment for several years. Manufacturers must therefore combine participation expansion with product upgrades, complementary consumables, accessories, and premium equipment to support recurring revenue.
Top Players in Racket Sports Market
- Yonex
- Wilson Sporting Goods
- HEAD
- Babolat
- ASICS
- DECATHLON
- Li-Ning
- Victor
- Butterfly
- Stiga
- Tecnifibre
- Prince Sports
- Dunlop Sports
- Gamma Sports
- Solinco
- Adidas
- Nike
- Puma
- Mizuno
- FZ Forza
- Carlton Sports
- Joola
- Selkirk Sport
- Kuikma
Racket Sports Market Segments
By Sport
- Tennis
- Badminton
- Padel
- Table Tennis
- Squash
- Pickleball
- Other Racket Sports
By Product Type
- Rackets & Paddles
- Balls & Shuttlecocks
- Strings & Grips
- Bags & Protective Equipment
- Apparel & Footwear
By Distribution Channel
- Online
- Specialty Sports Stores
- Sporting Goods Retailers
- Clubs & Academies
By Player Type
- Recreational Players
- Competitive & Professional Players
- Junior Players
- School & Institutional Players
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM
Conclusion
The global Racket Sports Market is projected to grow from USD 348.31 million in 2026 to USD 414.87 million by 2034 at a CAGR of 2.21%. Expansion of racket-sport participation, growth of padel and pickleball, youth development programs, sports infrastructure, and technology-led equipment innovation are supporting market expansion.
Tennis currently leads the Sport segment with approximately 38% share, while Padel is projected to grow fastest at approximately 11.6% CAGR. Rackets & Paddles account for approximately 44% of the Product Type segment, while Balls & Shuttlecocks are projected to grow at approximately 3.4% CAGR. Recreational Players lead the Player Type segment with approximately 61% share, while Junior Players are projected to grow at approximately 4.6% CAGR. North America remains the dominant regional market with approximately 31% share, while APAC is projected to record the fastest regional growth at approximately 4.8% CAGR through 2034.
Report Link: